
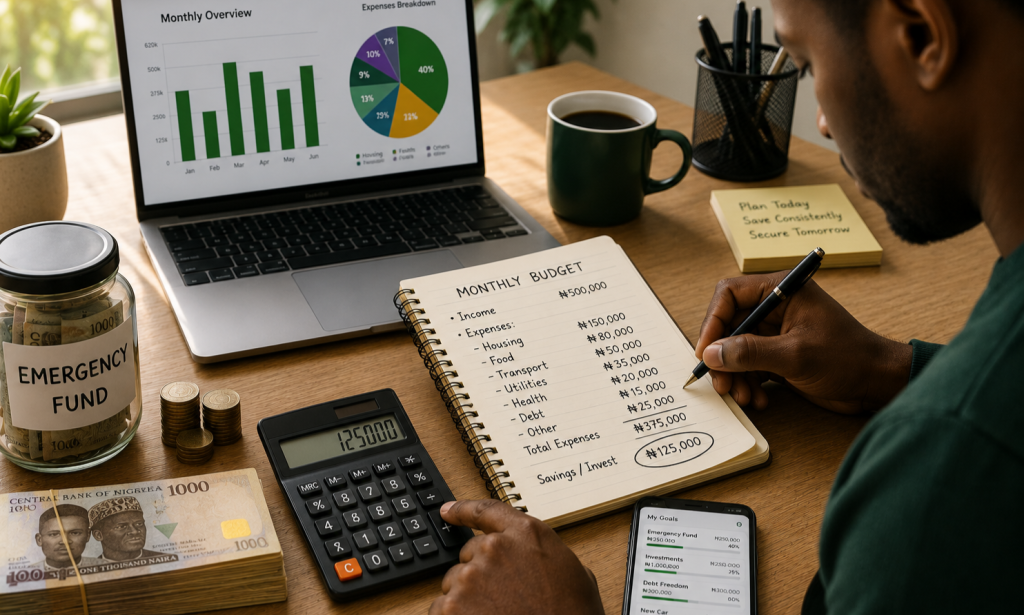
If you earn ₦500,000 a month, how much should you actually save?
You will find plenty of simple answers online.
Save 10%.
Save 20%.
Save 30%.
Invest half your income.
The problem is that none of those percentages automatically tells you what is right for your situation.
Someone earning ₦500,000 and living alone may have very different financial obligations from someone earning the same amount while supporting a spouse, children or other family members.
So the better question is not:
“What percentage of ₦500,000 should everyone save?”
It is:
“How much of my ₦500,000 can I save consistently while still covering my important expenses and building financial security?”
For some people, that might be ₦25,000 a month.
For others, it could be ₦100,000, ₦150,000 or more.
The goal is not to find an impressive percentage.
The goal is to build a financial system you can actually maintain.
First, Know Where Your ₦500,000 Is Going
Before deciding how much to save, look at what happens to your money after your salary arrives.
A simple starting point is to divide your spending into three groups:
Essential expenses
These are things you need to keep paying, such as housing, food, transportation, utilities, healthcare and minimum debt payments.
Financial priorities
These include emergency savings, investments, debt repayment and other important financial goals.
Discretionary spending
These are things you may enjoy but could reduce or postpone if necessary, such as entertainment, eating out, subscriptions, shopping and some lifestyle expenses.
This type of budgeting matters because the CBN's financial-literacy framework specifically encourages people to create and follow a budget and prioritize spending according to pressing needs rather than wants.
You cannot decide whether ₦100,000 is a reasonable monthly saving target until you know whether your essential expenses are ₦250,000 or ₦450,000.
Is Saving 20% of ₦500,000 a Good Target?
Twenty percent of ₦500,000 is:
₦500,000 × 20% = ₦100,000
Saving ₦100,000 every month would mean:
₦100,000 × 12 = ₦1.2 million per year
That is a strong result if you can genuinely afford it.
But 20% should not be treated as a rule that everyone earning ₦500,000 must follow.
Imagine someone earning ₦500,000 who has:
- high rent
- children to support
- significant transport costs
- medical expenses
- family obligations
- debt repayments
Saving ₦100,000 every month may simply be unrealistic.
Another person earning the same ₦500,000 with lower expenses might comfortably save ₦150,000 or more.
The same salary does not create the same financial situation.
What Is a Realistic Amount to Save From ₦500,000?
Rather than giving one answer, it is more useful to look at different situations.
| Monthly saving | Percentage of ₦500,000 | Annual saving |
|---|---|---|
| ₦25,000 | 5% | ₦300,000 |
| ₦50,000 | 10% | ₦600,000 |
| ₦75,000 | 15% | ₦900,000 |
| ₦100,000 | 20% | ₦1.2 million |
| ₦125,000 | 25% | ₦1.5 million |
| ₦150,000 | 30% | ₦1.8 million |
| ₦200,000 | 40% | ₦2.4 million |
These are simple calculations, not recommendations.
The important thing is to understand what each target would require from your monthly budget.
For someone struggling to meet essential expenses, ₦25,000 might be a significant achievement.
For someone with relatively low expenses, ₦150,000 may be entirely achievable.
If You Earn ₦500,000, Start With Your Essential Expenses
Suppose your monthly salary is ₦500,000 and your essential expenses look like this:
| Expense | Monthly amount |
|---|---|
| Housing | ₦120,000 |
| Food | ₦80,000 |
| Transportation | ₦50,000 |
| Utilities and communication | ₦35,000 |
| Healthcare | ₦20,000 |
| Family obligations | ₦30,000 |
| Minimum debt payments | ₦15,000 |
| Total essential expenses | ₦350,000 |
That leaves:
₦500,000 − ₦350,000 = ₦150,000
You now have ₦150,000 before considering discretionary spending and other financial goals.
You could decide to allocate part of that amount to emergency savings, part to investing and part to personal spending.
The exact split depends on your priorities.
But the important discovery is that you now know why you can or cannot save a particular amount.
What If Your Expenses Are ₦450,000?
Now consider a different person earning exactly the same ₦500,000.
Their essential expenses might total ₦450,000.
That leaves only:
₦500,000 − ₦450,000 = ₦50,000
If they try to save ₦150,000 every month, they would need to cut essential spending, borrow money or fall behind on their obligations.
That is not sustainable.
Saving ₦25,000 or ₦30,000 consistently may be much more realistic.
This is why financial advice based only on percentages can be misleading.
Your savings rate should fit your actual cash flow.
What If You Are Supporting a Family?
A ₦500,000 salary can look very different depending on how many people depend on it.
Consider someone who is single and someone who supports a family of five.
Their income is the same.
Their financial responsibilities are not.
If you support a family, your budget may need to account for:
- children's expenses
- school-related costs
- healthcare
- food for more people
- transportation
- support for relatives
- housing
- unexpected family expenses
That does not mean you should stop saving.
It means your initial savings target may need to be more realistic.
You could start with ₦30,000 or ₦50,000 and increase the amount as your income grows.
What If You Have Debt?
Debt changes the calculation.
Suppose you earn ₦500,000 and have a high-interest loan requiring ₦100,000 in monthly payments.
Simply deciding to save ₦100,000 without considering the cost of the debt may not be the best strategy.
At the same time, having no emergency savings at all can leave you vulnerable to another unexpected expense.
A reasonable approach may be to:
- Build a small emergency buffer.
- Continue making required debt payments.
- Focus aggressively on expensive debt.
- Increase emergency savings as the debt burden falls.
The correct balance depends on the type of debt, its interest rate, your income stability and your existing savings.
There is no rule that says you must choose between “save nothing” and “save everything.”
How Much Should Go to Emergency Savings?
If you are starting from zero, emergency savings should usually be one of your first financial priorities.
The CFPB describes an emergency fund as money set aside for unexpected expenses or financial emergencies and notes that even a small amount can provide some financial security.
For a deeper guide, read How Much Should You Have in an Emergency Fund?.
Suppose you earn ₦500,000 and can comfortably save ₦100,000 each month.

You could initially direct a significant portion of that amount toward your emergency fund.
For example:
₦100,000 monthly savings
→ Build first financial buffer
→ Reach ₦100,000
→ Reach ₦250,000
→ Reach one month of essential expenses
→ Work toward three months
Once your emergency fund is sufficiently established, you can redirect more of your monthly savings toward longer-term investments and other goals.
What If You Can Only Save ₦20,000 or ₦30,000?
Don't dismiss a small amount.
Saving:
₦25,000 × 12 = ₦300,000
Saving:
₦30,000 × 12 = ₦360,000
Saving:
₦50,000 × 12 = ₦600,000
The difference between having ₦0 and having ₦300,000 available for an emergency can be significant.
The CBN's financial-literacy guidance recognizes the importance of helping individuals generate and save income and cope with irregular income.
If your income is limited, see How to Build an Emergency Fund With a Low Income.
The objective is not to save a huge amount for three months and then give up.
A smaller amount that you can maintain is better than an aggressive target that constantly fails.
What If You Can Save ₦150,000 or More?
If your essential expenses are relatively low and you can comfortably save ₦150,000 every month, you have a valuable opportunity.
At ₦150,000 per month:
₦150,000 × 12 = ₦1.8 million
You could use that capacity to build your emergency fund quickly and then allocate future savings toward longer-term goals.
For example, after establishing an adequate emergency reserve, you might divide future savings between:
- long-term investments
- retirement
- property
- business
- education
- other major financial goals
The right allocation depends on your objectives and risk tolerance.
Don't Confuse Savings With Investing
This distinction matters.
Money you are saving for a short-term financial need and money you are investing for long-term growth should not automatically be treated the same way.
Your emergency fund needs to be accessible and relatively safe.
Long-term investment money can generally tolerate more fluctuation because you do not expect to need it immediately.
For example, if you have ₦500,000 that you may need next month for an emergency, putting all of it into an investment that can fall in value may expose you to unnecessary risk.
On the other hand, money you will not need for many years may have a different role.
Save for protection. Invest for long-term growth.
How Much Should You Have Left After Saving?
A savings target should not make your monthly life impossible.
Suppose you earn ₦500,000 and decide to save ₦150,000.
That leaves:
₦500,000 − ₦150,000 = ₦350,000
If your essential expenses already require ₦350,000, you have nothing left for discretionary spending, unexpected costs outside your emergency fund or other financial commitments.
That may be too aggressive.
A better target could be ₦100,000:
₦500,000 − ₦100,000 = ₦400,000
You now have more flexibility while still saving a significant amount.
The best savings target is one you can maintain month after month.
What About Rent?
Rent deserves special attention because it can distort monthly budgets.
Suppose your annual rent is ₦1.2 million.
It may be tempting to think of rent as ₦100,000 per month because:
₦1.2 million ÷ 12 = ₦100,000
But you may actually have to pay the full amount at once.
That means a person earning ₦500,000 should not simply divide annual rent by 12 and assume the cash-flow problem has disappeared.
A practical budget can treat rent as a monthly sinking fund:
₦1.2 million ÷ 12 = ₦100,000 per month set aside
This gives you a clearer picture of what your income is actually committed to.
How to Increase Your Savings Without Earning More
You do not necessarily need a salary increase to improve your savings rate.
Look at your existing spending first.
For example, suppose you currently save ₦50,000.
You identify:
- ₦10,000 of unused subscriptions
- ₦15,000 of unnecessary recurring expenses
- ₦10,000 of avoidable food spending
If you redirect that ₦35,000 toward savings:
₦50,000 + ₦35,000 = ₦85,000
You have increased your savings without receiving a pay raise.
This is why tracking actual spending matters.
The CBN's financial-literacy framework emphasizes budgeting and prioritizing spending rather than simply earning more money.
What Should You Do When Your Salary Increases?
This is where many people lose the benefit of a pay rise.
Suppose your salary increases from:
₦500,000 → ₦650,000
Your income has increased by:
₦150,000
You could immediately increase your lifestyle by ₦150,000.
Or you could decide to direct part of the increase toward your financial goals.
For example:
₦50,000 → emergency savings
₦50,000 → investments
₦50,000 → improved lifestyle
There is no requirement to use this exact split.
The point is to avoid allowing every income increase to disappear into higher spending.
This is sometimes called lifestyle inflation: as income rises, spending rises with it.
A Simple ₦500,000 Salary Budget
There is no perfect budget for everyone, but here's one hypothetical example.
| Category | Amount | Percentage |
|---|---|---|
| Essential expenses | ₦300,000 | 60% |
| Emergency savings | ₦75,000 | 15% |
| Long-term investing | ₦50,000 | 10% |
| Personal/discretionary spending | ₦50,000 | 10% |
| Flexible buffer | ₦25,000 | 5% |
| Total | ₦500,000 | 100% |
This is not a universal recommendation.
Someone supporting a large family might need to spend more than 60% on essentials.
Someone living alone might be able to save substantially more.
The purpose of the example is to show that a budget should give every naira a job.
What If You Earn ₦500,000 but Live in an Expensive City?
Location matters.
A ₦500,000 salary does not necessarily provide the same standard of living everywhere.
Housing, transportation, food and other costs can vary significantly by city and household.
For example, recent Nigerian reporting on a 2026 Cowrywise cost-of-living model put basic independent living in Lagos around the ₦500,000–₦550,000 monthly range under its assumptions, while a more comfortable model was around ₦800,000–₦850,000. Those figures are specific to the report's assumptions and should not be treated as a universal Lagos budget.
This is another reason MoneyTrut should avoid telling every Nigerian earning ₦500,000 to save exactly the same amount.
Your location and living arrangement matter.
What Should Your First Goal Be?
If you earn ₦500,000 and have no savings, don't make your first target “become wealthy.”
Make it:
Build financial breathing room.
A practical progression could be:
₦50,000 emergency buffer
↓
₦100,000
↓
₦250,000
↓
One month of essential expenses
↓
Three months of essential expenses
↓
Long-term investing and other financial goals
Your exact numbers will depend on your expenses.
The important part is that each milestone reduces your financial vulnerability.
A Better Way to Think About Your ₦500,000 Salary
Instead of asking:
“How much can I spend from my ₦500,000?”
Ask:
“How much of this ₦500,000 should work for my future before I spend the rest?”
That does not mean you should deny yourself everything.
Money has several jobs.
It pays for today's needs.
It protects you against tomorrow's emergencies.
It can reduce debt.
And eventually, it can be invested to build wealth.
A good salary is useful.
But how you allocate it determines what that salary can actually do for you.
The Bottom Line
If you earn ₦500,000 a month, there is no universal amount you must save.
Saving 20%—₦100,000 per month—is a strong target if your budget can genuinely support it. But saving 10%, 15%, 25% or even another amount may be more appropriate depending on your circumstances.
Start by calculating your essential expenses.
Build an emergency fund if you do not already have one.
Pay attention to expensive debt.
Save consistently.
Then increase your savings when your income rises or your expenses fall.
At ₦500,000 a month, saving ₦50,000 gives you ₦600,000 over a year.
Saving ₦100,000 gives you ₦1.2 million.
Saving ₦150,000 gives you ₦1.8 million.
The number matters—but consistency matters more.
The goal isn't to find the percentage that looks best on social media.
The goal is to build a financial life where your ₦500,000 salary does more than get you through the month.

You must be logged in to post a comment.