
A small business can be profitable on paper and still struggle to pay its bills.
You may have ₦500,000 worth of sales for the month, but if customers have only paid ₦250,000 and you need ₦300,000 to restock, you already have a cash-flow problem.
This is why business owners need to understand the difference between profit and cash flow.
Profit tells you whether your business generated more revenue than its costs over a period.
Cash flow tells you how money is actually moving into and out of the business.
For a small business in Nigeria, managing cash flow can become especially important when customers buy on credit, suppliers require payment before delivery, costs change frequently or sales are irregular.
The good news is that cash-flow management does not have to be complicated.
A small business can start with a simple system for tracking money coming in, money going out, money owed to the business and upcoming obligations.
What Is Cash Flow?
Cash flow simply refers to money moving into and out of your business.
Cash inflows
These are amounts entering the business, such as:
- Customer payments
- Cash sales
- Bank transfers from customers
- Payments for services
- Business loans
- Capital introduced by the owner
- Other legitimate business receipts
Cash outflows
These are amounts leaving the business, such as:
- Stock purchases
- Raw materials
- Rent
- Salaries
- Transport
- Electricity
- Advertising
- Equipment purchases
- Supplier payments
- Loan repayments
- Other operating expenses
A simple cash-flow calculation is:
Cash Inflows − Cash Outflows = Net Cash Flow
If ₦800,000 enters the business during a month and ₦650,000 leaves:
₦800,000 − ₦650,000 = ₦150,000
Your net cash flow for that period is ₦150,000.
But that does not automatically mean you made ₦150,000 in profit.
Profit and Cash Flow Are Not the Same
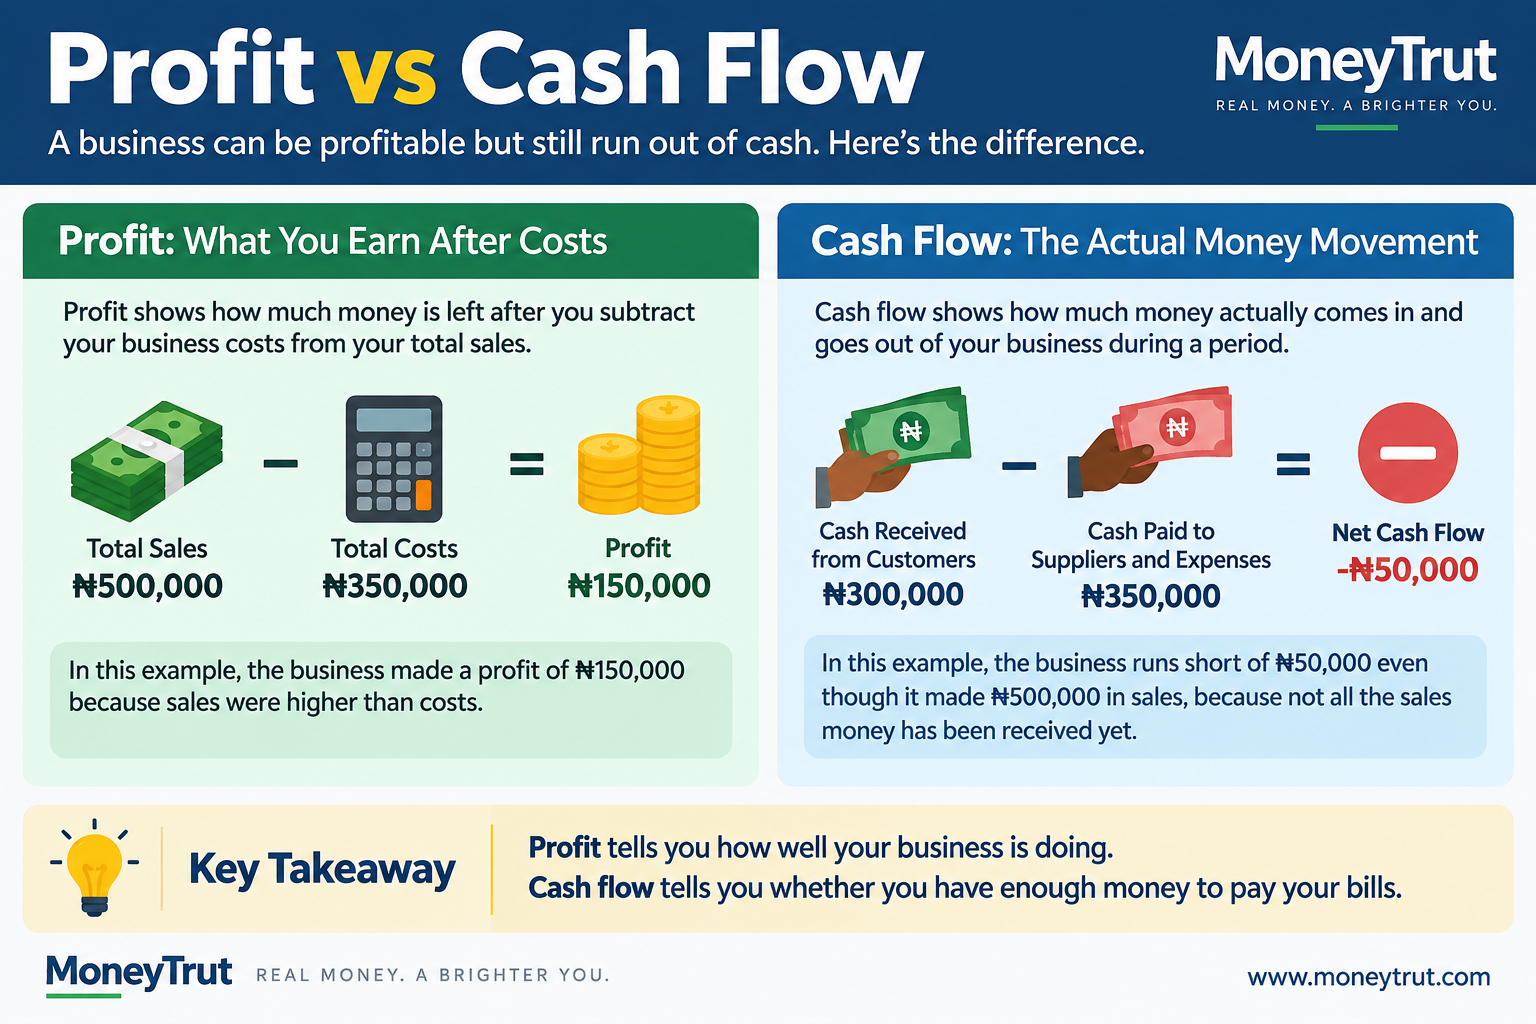
This is one of the most important concepts for a business owner to understand.
Imagine you sell ₦500,000 worth of products in September.
Customers have paid only ₦300,000 so far.
The remaining ₦200,000 is still owed to you.
Your records may show ₦500,000 in sales, but only ₦300,000 has actually entered your bank or cash register.
Now imagine your suppliers require ₦350,000 in September.
You have:
Cash available from customers: ₦300,000
Supplier payment required: ₦350,000
You are short:
₦50,000
The business may have made sales, but it still has a cash-flow problem.
This is why a business owner should not judge the financial health of the business by sales or profit alone.
Why Cash Flow Matters for Small Businesses
Large businesses may have access to significant financing and cash reserves.
A small business may not have the same flexibility.
If you run a small shop, food business, fashion business, service business or online store, missing a payment can quickly affect your ability to operate.
You may need cash to:
- Restock
- Pay suppliers
- Pay workers
- Pay rent
- Deliver customer orders
- Repair equipment
- Pay for electricity
- Maintain your online presence
- Cover unexpected expenses
If your cash is tied up in unpaid customer invoices or unsold inventory, you may struggle even when the business appears busy.
Start by Tracking Your Cash Every Week
You do not need complicated accounting software to begin.
Create a simple weekly cash-flow record.
For example:
| Item | Amount |
|---|---|
| Opening cash | ₦150,000 |
| Customer payments | ₦350,000 |
| Other business receipts | ₦50,000 |
| Total cash available | ₦550,000 |
| Stock purchases | ₦200,000 |
| Transport | ₦40,000 |
| Salaries | ₦100,000 |
| Other expenses | ₦60,000 |
| Closing cash | ₦150,000 |
The exact categories will depend on your business.
The important thing is knowing where the money came from and where it went.
This builds directly on MoneyTrut's earlier guide on how to keep business records in Nigeria.
Know Your Opening and Closing Cash
At the beginning of each week or month, record how much cash the business has available.
Suppose you start the month with:
₦200,000
During the month, customers pay:
₦700,000
Total available:
₦900,000
You then spend:
₦650,000
Your estimated closing cash is:
₦900,000 − ₦650,000 = ₦250,000
That ₦250,000 becomes your starting cash for the next period, before considering other balances or restricted funds.
This simple calculation can help you avoid spending money that the business will soon need.
Don't Treat Every Bank Balance as Available Money
Seeing ₦500,000 in a business account does not necessarily mean you have ₦500,000 available to spend.
Suppose you have:
Bank balance: ₦500,000
But you know:
- ₦150,000 is needed to pay a supplier
- ₦100,000 is needed for salaries
- ₦50,000 is needed for rent
- ₦50,000 is required to fulfil existing customer orders
That leaves:
₦150,000
as potentially available cash before considering other obligations.
This is why cash-flow management requires you to look ahead.
Create a List of Upcoming Payments
At the beginning of each month, write down major payments that are expected.
For example:
| Payment | Amount | Due |
|---|---|---|
| Rent | ₦120,000 | Sept. 10 |
| Supplier | ₦180,000 | Sept. 15 |
| Salaries | ₦150,000 | Sept. 25 |
| Electricity | ₦40,000 | Sept. 27 |
| Internet | ₦15,000 | Sept. 28 |
Total upcoming obligations:
₦505,000
Now compare that with expected cash inflows.
If you expect only ₦350,000 in customer payments before those dates, you already know there may be a shortfall.
That gives you time to act.
You could:
- Collect outstanding customer payments
- Delay non-essential spending
- Negotiate payment timing with a supplier
- Increase sales efforts
- Reduce inventory purchases
- Arrange appropriate financing where necessary
Finding the problem early is much better than discovering it when a payment is already due.
Keep Track of Money Customers Owe You
Credit sales can create serious cash-flow problems.
Suppose you sell:
₦1,000,000 worth of products
but customers owe you:
₦400,000
Your sales may look strong, but ₦400,000 is still outside your immediate cash balance.
Keep a record of:
- Customer name
- Amount owed
- Date of sale
- Payment deadline
- Amount already paid
- Outstanding balance
Then follow up appropriately.
If customers consistently delay payments, you may need to reconsider your credit policy.
Set Clear Payment Terms
If you allow customers to pay later, make the terms clear before the transaction.
For example:
50% deposit before production
Balance due before delivery
or:
Payment due within seven days
The right arrangement depends on your industry and customer relationship.
The important point is that the customer should understand when payment is expected.
Unclear payment terms can turn into delayed payments.
Consider Taking Deposits for Custom Orders
Some businesses spend money before delivering a product.
For example, a fashion designer may need to purchase fabric before making a customer's outfit.
A furniture maker may need to buy wood.
A caterer may need to purchase ingredients for an event.
If you pay all the production costs yourself before receiving any customer payment, your cash can become tied up.
Where appropriate, a deposit can reduce this pressure.
For example:
Total order: ₦200,000
Customer deposit: ₦100,000
The business now has some of the cash required to begin fulfilling the order.
The exact deposit percentage should depend on the business, customer relationship, costs and applicable terms.
Don't Let Too Much Cash Get Trapped in Inventory
Inventory is useful because you need products available to sell.
But too much inventory can tie up your money.
Suppose you have:
₦1,000,000 in cash
You use:
₦800,000 to buy stock
You now have only:
₦200,000 in cash
The business may look well stocked, but it has much less cash available for:
- Rent
- Salaries
- Transport
- Emergencies
- Marketing
- Supplier payments
If the stock sells quickly, this may not be a problem.
But if the products remain unsold for months, a large portion of your money remains tied up.
This is why inventory management is also a cash-flow issue.
Don't Buy Stock Simply Because It Is Cheap
A supplier may offer a discount if you buy a large quantity.
That can be attractive.
Suppose buying 100 units reduces your cost from ₦5,000 to ₦4,500 per unit.
You could save:
₦500 × 100 = ₦50,000
But you have also spent:
100 × ₦4,500 = ₦450,000
If those products take a long time to sell, your ₦450,000 is tied up.
A discount is useful only if the inventory can be sold at a reasonable pace and the business can afford the cash outlay.
Negotiate Supplier Payment Terms Carefully
If your suppliers allow you to pay after receiving stock, that can sometimes improve cash flow.
For example:
You receive ₦300,000 worth of stock today.
The supplier allows you to pay in 30 days.
You may be able to sell some of the stock before the payment is due.
That can reduce the amount of your own cash tied up in inventory.
However, do not accept supplier credit simply because it is available.
You need to know:
- When payment is due
- Whether there are penalties
- Whether prices are higher on credit
- What happens if sales are slower than expected
Supplier credit should improve your business operations rather than create another problem.
Separate Essential and Non-Essential Expenses
When cash is tight, not every expense has the same priority.
For example:
Essential
- Employee wages
- Critical inventory
- Rent
- Utilities needed to operate
- Customer fulfilment
- Required business obligations
Potentially deferrable
- Non-essential equipment
- Office decoration
- Unnecessary subscriptions
- Large promotional expenses without evidence of return
- Personal spending
The exact priority depends on your business.
The point is to know which expenses are essential before cash becomes tight.
Don't Use Business Cash for Personal Spending Without Recording It
This is a common problem for small businesses.
Suppose your business has ₦300,000.
You need ₦50,000 for personal expenses.
You transfer the money from the business account.
If you do not record the transaction, your business records may later appear confusing.
Was the ₦50,000 a business expense?
Was it a supplier payment?
Was it an owner's withdrawal?
The business should have a clear record.
Our earlier article on how to manage your money when you have multiple sources of income also discusses the importance of having a system for handling money from different sources.
Create a Business Cash Reserve
A business can experience unexpected expenses.
A machine may break down.
A supplier may increase prices.
A major customer may delay payment.
Sales may fall for a month.
A cash reserve can provide some protection.
There is no single amount that every business should keep.
Your reserve should depend on:
- Business size
- Monthly expenses
- Income stability
- Industry
- Supplier terms
- Customer payment patterns
- Access to financing
For example, a business with monthly essential expenses of ₦300,000 may decide that maintaining ₦300,000 to ₦600,000 of readily available business cash would provide a useful buffer, depending on its circumstances.
The important thing is that the reserve should be money the business can actually access when needed.
Build a Simple Cash-Flow Forecast
A cash-flow forecast estimates how much money you expect to receive and spend during a future period.
For example:
| Week | Expected Inflows | Expected Outflows | Expected Net |
|---|---|---|---|
| Week 1 | ₦250,000 | ₦180,000 | ₦70,000 |
| Week 2 | ₦200,000 | ₦250,000 | -₦50,000 |
| Week 3 | ₦350,000 | ₦200,000 | ₦150,000 |
| Week 4 | ₦300,000 | ₦220,000 | ₦80,000 |
The important figure is not only the monthly total.
Week 2 shows a potential ₦50,000 shortfall.
If you identify that before the week arrives, you have time to prepare.
This is one of the main benefits of cash-flow forecasting.
Use Conservative Sales Estimates
When preparing a cash-flow forecast, do not assume every potential sale will happen.
Suppose your business usually receives between ₦300,000 and ₦500,000 per month.
It may be risky to build your forecast around ₦500,000 every month.
A more conservative estimate may be appropriate, particularly when income is unpredictable.
You can then compare:
Expected case
Conservative case
Strong sales case
This gives you a better idea of what happens under different conditions.
Separate Expected Cash From Confirmed Cash
This is an important habit.
Suppose a customer tells you:
"I'll pay ₦200,000 next Friday."
That ₦200,000 is expected.
It is not yet cash.
Until the money is actually received, there is a risk that:
- Payment is delayed
- The order is cancelled
- The customer changes the arrangement
- The amount is reduced
Therefore, when forecasting, distinguish between:
Cash already received
and
Cash expected
This prevents you from spending money before you actually have it.
Watch Your Cash Conversion Cycle
Some businesses spend money long before they receive money from customers.
For example:
Day 1: Buy materials
Day 5: Produce goods
Day 10: Deliver to customer
Day 30: Customer pays
Your money may be tied up for a significant period.
The longer the gap between paying suppliers and receiving customer money, the more working capital your business may need.
You can improve this cycle by:
- Collecting deposits
- Reducing unnecessary inventory
- Selling faster
- Collecting customer payments promptly
- Negotiating reasonable supplier terms
The exact approach depends on your business model.
Don't Chase Sales That Make Cash Flow Worse
More sales are not always automatically better.
Imagine a customer wants ₦500,000 worth of goods.
But the customer insists on paying 90 days later.
Meanwhile, you need to pay your supplier immediately.
If your business does not have enough working capital, accepting the order could create cash-flow pressure.
The sale may eventually be profitable, but you need to ask:
Can the business afford to wait for the payment?
This is another reason why pricing and cash-flow decisions should be considered together.
Watch Your Gross Margin
A business with a very small margin has less room to absorb cash-flow problems.
Suppose you sell a product for ₦10,000.
Your direct cost is ₦9,000.
Your gross contribution is only:
₦1,000
You may need to sell a large number of products to generate enough money to cover other expenses.
Compare that with a product selling for ₦10,000 with a direct cost of ₦6,000.
Contribution:
₦4,000
This does not automatically make the second business better because other costs and demand also matter.
But it shows why understanding margins matters when managing cash flow.
Our break-even guide explains how selling price, variable costs and fixed costs affect the amount a business needs to sell.
Keep Business Records Up to Date
Cash-flow management becomes difficult when your records are several weeks behind.
If you don't know:
- What customers owe
- What you owe suppliers
- What you spent
- What you sold
- What cash is available
you cannot accurately forecast your position.
A simple record updated consistently is more useful than a complicated system that you never maintain.
MoneyTrut's guide to keeping business records provides a practical starting system for small businesses.
Review Cash Flow Every Week
You do not need to wait until the end of the month.
Once a week, ask:
How much cash do we have?
How much money should come in?
Who owes us?
Who do we owe?
What major payments are due?
What expenses can be delayed?
Do we need to buy more stock?
Are sales moving as expected?
A 20-minute weekly review can help you identify problems before they become emergencies.
A Simple Monthly Cash-Flow Example
Suppose a small business begins the month with:
Opening cash: ₦250,000
Expected customer payments:
₦800,000
Total available:
₦1,050,000
Expected payments:
- Stock: ₦400,000
- Salaries: ₦200,000
- Rent: ₦100,000
- Transport: ₦80,000
- Electricity: ₦40,000
- Marketing: ₦50,000
- Other expenses: ₦50,000
Total outflows:
₦920,000
Expected closing cash:
₦1,050,000 − ₦920,000 = ₦130,000
The business may therefore expect to finish the month with approximately ₦130,000 in cash.
But there is another question:
What happens if customers pay only ₦650,000 instead of ₦800,000?
Available cash becomes:
₦250,000 + ₦650,000 = ₦900,000
Expected outflows remain:
₦920,000
Potential shortfall:
₦20,000
That simple scenario shows why forecasting matters.
What to Do When Cash Flow Is Tight
If you discover that your business may run short of cash, act early.
1. Collect outstanding payments
Follow up with customers who owe you.
2. Delay non-essential expenses
Protect cash needed for essential operations.
3. Review inventory purchases
Do not buy more stock than you can reasonably sell.
4. Talk to suppliers
Where appropriate, negotiate payment timing before the due date rather than after missing it.
5. Increase sales strategically
Focus on products or services that generate useful contribution and can be sold without requiring excessive additional cash.
6. Review pricing
If your costs have increased significantly, your pricing may need to be reassessed.
7. Consider financing carefully
A loan may solve a temporary cash-flow problem, but it can also create another obligation.
Do not borrow simply to hide an underlying business problem.
Be Careful With Business Loans
Borrowing can sometimes be appropriate for working capital, equipment or expansion.
But a business should understand the repayment obligation before taking on debt.
Suppose you borrow ₦1 million and must repay ₦100,000 every month.
You need to ask:
Can the business reliably generate enough cash to make that payment?
Do not base the answer only on your best sales month.
Use your actual records and conservative forecasts.
SMEDAN's current support ecosystem includes access to finance and business-development resources for MSMEs, but financing should still be evaluated based on the business's ability to repay it.
Don't Use Short-Term Cash for Long-Term Purchases Without Planning
Suppose your business has ₦1 million in cash.
You use ₦800,000 to buy equipment.
The equipment may be useful for years.
But you now have only ₦200,000 available for immediate business needs.
If monthly operating expenses are ₦300,000, you have created a potential cash-flow problem.
Before making large purchases, ask:
How much cash will remain after the purchase?
What payments are due soon?
How quickly will the purchase generate additional cash?
Can the business operate comfortably while waiting for the investment to pay off?
Grow Without Destroying Your Cash Flow
Growth can actually increase cash-flow pressure.
Imagine your monthly sales increase from:
₦500,000 → ₦1,000,000
That sounds excellent.
But to support the higher sales, you may need:
- More inventory
- More workers
- More packaging
- More transport
- More advertising
- Larger premises
You may therefore need more working capital before receiving all the cash from the additional sales.
This is why fast growth is not automatically healthy growth.
A business needs enough cash to support its expansion.
SMEDAN's current enterprise-growth programmes also focus on scaling businesses while improving their operational capacity and competitiveness.
A Simple Cash-Flow Checklist
At the beginning of every week, check:
Cash available: ₦________
Customer payments expected: ₦________
Customer payments overdue: ₦________
Supplier payments due: ₦________
Salaries due: ₦________
Rent and utilities due: ₦________
Expected stock purchases: ₦________
Other major expenses: ₦________
Expected closing cash: ₦________
If the expected closing cash becomes uncomfortably low, do not wait until the money runs out.
Investigate the problem immediately.
Five Cash-Flow Mistakes to Avoid
1. Spending based on sales instead of available cash
A sale is not necessarily cash in your account.
2. Allowing too much customer credit
Unpaid sales can create pressure even when revenue looks strong.
3. Buying too much inventory
Stock sitting on a shelf cannot pay your bills until it is sold.
4. Mixing business and personal spending
This makes it difficult to understand the business's true cash position.
5. Waiting until there is a crisis
Cash-flow problems are easier to manage when identified early.
Bottom Line
Cash flow is one of the most important financial numbers for a small business.
You need to know not only whether the business is profitable, but also whether it has enough cash available to pay its obligations when they become due.
Start with a simple system:
Track money coming in.
Track money going out.
Record what customers owe you.
Record what you owe suppliers.
Forecast major upcoming payments.
Keep an appropriate cash reserve.
Review the numbers every week.
A business does not become financially healthy simply because sales are increasing.
The real goal is to build a business where sales, profit and cash flow work together.
When you understand where your cash is coming from, where it is going and what will happen next, you can make better decisions about stock, pricing, expenses, borrowing and growth.
Related Articles
- How to Keep Business Records in Nigeria: A Simple System for Small Businesses
- How to Calculate the Break-Even Point for a Small Business in Nigeria
- How to Price Your Products and Services in Nigeria Without Losing Money
- How to Get Customers for a Small Business in Nigeria: Practical Ways That Work
- How to Start a Small Business in Nigeria With Little Money

You must be logged in to post a comment.